Semiconductor stocks sit at the intersection of two moving targets: who is buying them, and what their cash flows are worth in a changing macro environment. In one quarter, large institutions dominate flows and free cash flow (FCF) yields look attractive versus bond yields. In another, retail flows surge, multiples expand, and FCF yields compress as rates rise. If you want to understand where you are in the cycle—not just price, but positioning and valuation—you need a framework that connects buyer scale and FCF yield to the macro levers of interest rates, exchange rates, credit, and commodities.
This post lays out a quarterly tracking framework for semi buyer scale and FCF yield, and how to read their macro linkage. The tone is intentionally flexible: part quantitative, part narrative, because this is less about one perfect metric and more about a repeatable way of taking the temperature of the semi sector every quarter.
Two Pillars: Buyer Scale and FCF Yield
At the core of the framework are two pillars:
- Buyer scale: Who is actually buying and selling semi equities—by type and size. Are flows dominated by large long‑only institutions, hedge funds, quant funds, retail, or corporate buybacks? What is the relative scale of each?
- FCF yield: The free cash flow generated by semi companies relative to their market value. Formally, FCF yield = (FCF per share / price per share), often annualized. It’s a cash‑based counterpart to earnings yield.
Buyer scale tells you about positioning and sentiment; FCF yield tells you about valuation relative to cash flows and, indirectly, to macro benchmarks like bond yields. Tracking both together, quarter by quarter, reveals how macro conditions flow through both investor behaviour and fundamental value.
Macro Linkages That Shape the Framework
Before building the tracking framework, we need to acknowledge the macro levers that constantly shift the backdrop:
- Interest rates: Policy rates and yield curves set the discount rate for future cash flows and the attractiveness of FCF yields versus bond yields.
- Exchange rates: FX moves affect the earnings, margins, and perceived risk for global semi companies, influencing both FCF and foreign buyer behaviour.
-
Tight or wide credit conditions determine how easily semi companies can fund capex and how attractive their equity risk premium looks relative to debt. - Commodities and input costs: Energy and material price cycles affect manufacturing costs and free cash flow margins for many semi firms.
A quarterly tracking framework doesn’t replace these macro variables; it organizes how they show up in semi buyer scale and FCF yield. Each quarter, you’re essentially asking: how have rates, FX, credit, and commodities shifted, and how do those shifts appear in who is buying semis and what cash flows are being priced at?
Step 1: Define Buyer Scale Metrics
First, we need a way to measure “buyer scale” that’s practical and repeatable. Key metrics include:
- Ownership by investor type: Quarterly shifts in holdings by:
- Large long‑only institutions (pension funds, mutual funds).
-
Net inflows/outflows into semi sector funds and ETFs, turnover rates, and trading volumes relative to history. -
Changes in average trade size can indicate whether big players or smaller accounts are dominating activity.
Each quarter, you can summarize buyer scale as a set of scores or qualitative notes:
- “Institutional overweight, retail muted” vs “Retail dominant, institutions trimming.”
Step 2: Track and Contextualize FCF Yield
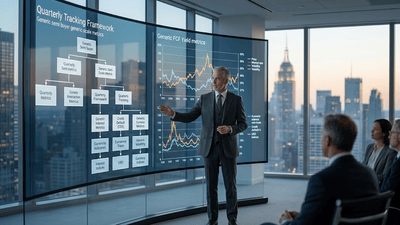
Second, we track FCF yield at the sector and sub‑sector level:
-
-
-
Changes in FCF yield quarter‑to‑quarter and relative to a multi‑year average. Rising FCF yields can indicate lower valuations, higher cash flow, or both; falling yields often reflect higher prices or weaker cash generation.
FCF yield can be viewed as the semi sector’s “cash bond” rate for equity investors. If semi FCF yields are high relative to bond yields, the sector may offer attractive cash‑based return potential. If FCF yields are low relative to bonds, you’re paying more for growth and narrative. Tracking this quarterly, alongside buyer scale, reveals whether investors are paying up for or demanding compensation for owning semi cash flows.
Step 3: Overlay Interest Rate and Yield Curve Data
With buyer scale and FCF yield in place, we overlay interest rate data:
-
Where are central bank rates now, and where does the market expect them to go? -
Steep, flat, or inverted? This shapes how future semi cash flows are discounted and whether near‑term or long‑term earnings are favoured. -
Nominal yields minus inflation expectations. Real yields are a key driver of valuation multiples for growth assets like semis.
Quarterly, you can make simple comparisons:
Step 4: Factor in FX, Credit, and Commodities
Next, bring in the other macro levers:
-
FX moves affect semi firms’ revenues and margins. A stronger dollar can pressure non‑US earnings but attract dollar‑based investors; a weaker dollar can support global demand and valuations. -
Tight spreads make debt financing cheaper, supporting capex and growth stories; wide spreads increase funding risk for smaller or leveraged semis. -
Higher energy and materials costs compress margins and reduce FCF; lower costs can expand FCF.
Quarterly tracking should note these macro conditions alongside buyer scale and FCF yield. For example: “FCF yields up due to margin pressure and price corrections; credit spreads widening; FX stable; buyer scale showing hedge fund selling and long‑only accumulation.” That combination tells a richer story than valuation alone.
Step 5: Build a Quarterly Dashboard
Putting this together, your quarterly framework becomes a dashboard with at least four panels:
-
Summary of which investor types are net buyers or sellers, and how flows and turnover look vs recent history. -
Sector and sub‑sector FCF yields relative to: -
Key readings on: -
A qualitative synthesis:
This dashboard doesn’t tell you what to do in one number; it gives you a structured way to judge whether semi exposure aligns with macro reality and investor behaviour. It’s a living framework you refresh every quarter.
Using the Framework: Examples Across Macro Regimes
Let’s walk through a few stylized quarterly scenarios:
Scenario A: Low Rates, Tight Credit Spreads, Strong Growth
-
-
Large institutions and growth funds increasing exposure; hedge funds trading actively; retail participation rising via ETFs. -
Semi sector FCF yields modest (prices high), but still above or comparable to bond yields.
Interpretation: Semi equities in a classic risk‑on, low‑rate regime. Quarterly framework suggests valuations are stretched but supported by macro and buyer scale. Strategy may be to stay invested, focusing on quality and secular winners, while watching for signs of IPO heat or sentiment excess.
Scenario B: Rising Real Yields, Widening Credit Spreads
-
-
Hedge funds and fast money reduce exposure; mutual funds move toward neutral; buybacks slower; retail flows wane. -
FCF yields rise as prices fall and cash flows normalize; relative to bond yields, the equity risk premium shrinks or becomes uncertain.
Interpretation: Macro turning risk‑off; funding conditions deteriorate. Quarterly framework suggests caution. Semis could be entering a value zone, but buyer scale and credit stress argue for selective exposure and patience rather than aggressive buying.
Scenario C: Post-Correction, Policy Easing, Stabilizing Credit
-
-
Long‑only and value funds slowly adding; hedge funds selectively re‑enter; buybacks resume; retail cautious but present. -
Elevated FCF yields vs bonds and IG credits; improving margins; pipeline demand visible (AI, new product cycles).
Interpretation: Potential early innings of a recovery. Quarterly framework suggests semi equities may offer attractive FCF yields in a more accommodative macro regime, with buyer scale signaling the beginning of renewed conviction. This could be a more favourable environment for expanding semi exposure.
Benefits and Limits of the Quarterly Approach
Benefits:
Limits:
-
-
Buyer scale metrics (ownership, flows) may be lagged or imperfect; FCF yield estimates can be noisy in fast‑moving earnings environments. -
Macro regimes are fluid; over‑reliance on past patterns can mislead if structural changes (policy frameworks, tech adoption) alter relationships.
Recognizing these limits, the framework is best used as a high‑level compass rather than a precise GPS. It tells you where risk and valuation have been drifting each quarter, not exactly where they will go next.
Closing Thoughts: Making Semi Exposure Macro-Aware, Quarter by Quarter
“A Quarterly Tracking Framework for Semi Buyer Scale and FCF Yield” is about giving semi investors a way to integrate macro linkages into their sector view without getting lost in daily noise. By tracking who owns the sector and what its cash flows are being valued at, in the context of rates, FX, credit, and commodities, you build a richer picture of where semis sit in the risk and valuation spectrum each quarter.
Semiconductors will remain core to the global economy; their stocks will remain volatile. A quarterly macro‑aware framework doesn’t make them safer, but it makes your decisions about them more grounded. It helps you see when you’re buying into a story supported by both cash flows and macro, and when you’re chasing buyer flows into a sector whose FCF yield no longer compensates you for the risks implied by the interest rate, exchange rate, credit, and commodity backdrop. In an environment where tech and macro are permanently intertwined, that kind of disciplined, flexible tracking is a worthwhile habit to cultivate.